The Fed Outsourced its Signal
Kevin Warsh's first genuinely live meeting as Fed Chair ended not with a new dot plot but with the removal of one.
Last week's FOMC held the target range and delivered a terse statement with no Summary of Economic Projections and no forward guidance — the Committee explicitly declined to pre-commit.
For a market that has spent two years trading the Fed's every syllable, that is a regime change. With nothing to price off the Fed's mouth, traders must price off the data instead. And the first full week of August could not be more loaded.
The Weekend Already Moved the Odds
Before a single number prints, September has been repriced.
The weekend de-escalation in the Gulf — Trump calling off a strike on claims of a Hormuz framework, which Tehran denies — collapsed crude 5–6% and pulled the near-term inflation impulse out of the front end.
Hike odds that sat near 80% into the FOMC have eased toward the low-to-mid 60s. That drop is a function of oil, not labor. This week's data decides whether the softer-inflation narrative holds, or whether a still-tight jobs market forces the hike tail back onto the curve.
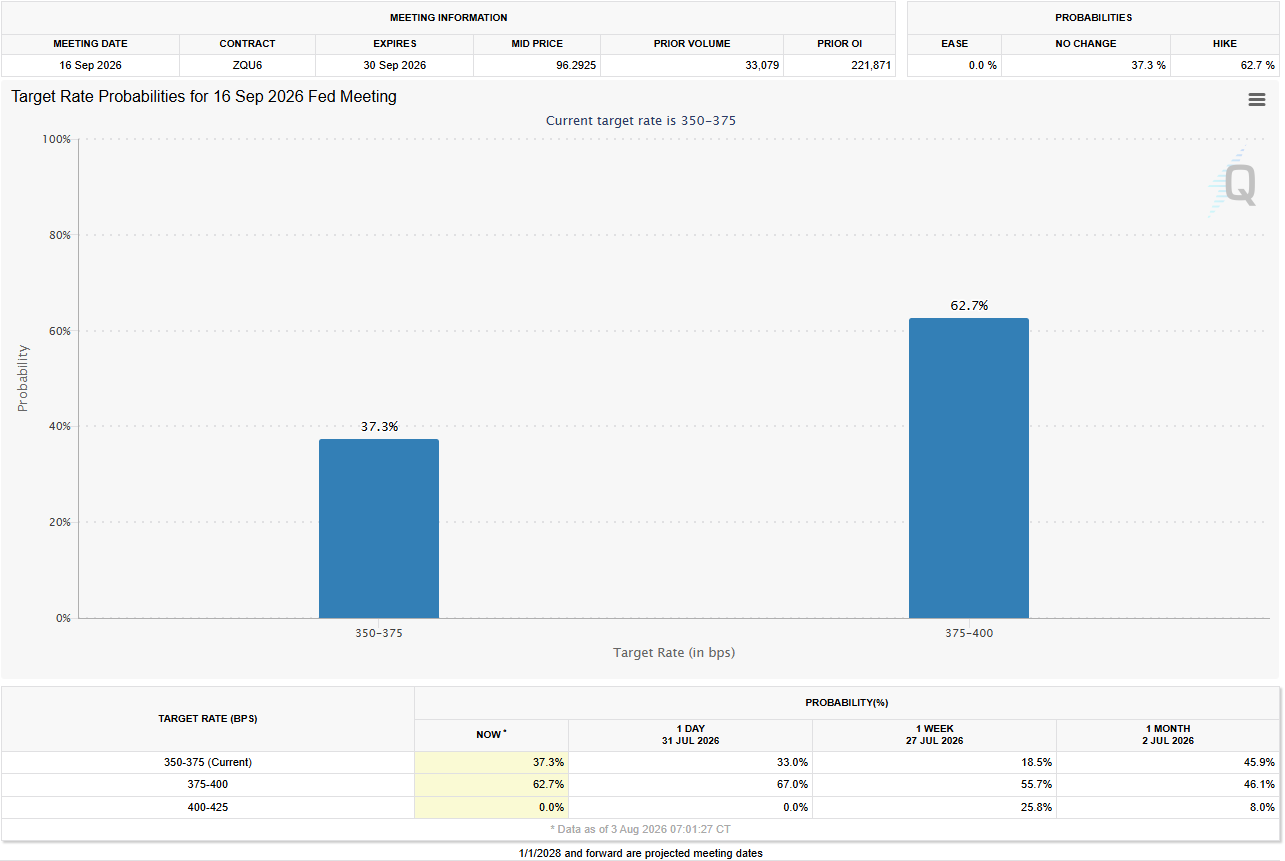
Source: CME FedWatch
Four Prints, One Question
The sequence is front-loaded and labor-heavy: ISM Manufacturing Monday, JOLTS Tuesday, ISM Services and ADP private paryrolls report Wednesday, jobless claims Thursday and July payrolls Friday.
The single thread through all four is whether June's air pocket — a startling +57k headline against 4.2% unemployment — was noise or the leading edge of genuine softening.
The Week's Map

Created by Zain Vawda Using Canva
The stagflationary tension is the trade: growth is cooling (Q2 GDP printed 1.5%) while inflation stays sticky (headline CPI 3.5%, core PCE 3.3%). A cold NFP with soft ISM prices-paid prices the hike out and rallies the front end; a hot NFP with firm prices revives it and lifts the 2-year. There is no benign middle — every release is a two-sided event now.
Scenario Matrix — Friday's Payrolls
The nearest binary is the 8:30 ET July employment report. Three lanes, each with its cross-asset readthrough:
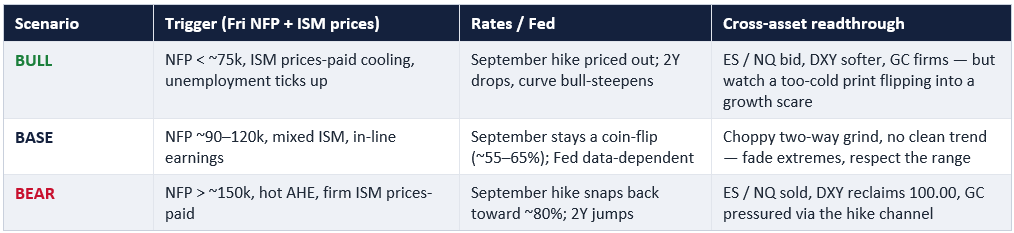
Created by Zain Vawda Using Canva
Markets remain sensitive as we have seen over the past few weeks. There is a constant change between what the key driver is and that is unlikely to change.
As the week gets underway, U.S. data may take a backseat to Middle East developments but the closer we get to the NFP release the greater the probability that this will be the key driver for market moves.


